The Definitive Guide to Comparing Orlando Insurance Quotes
The Definitive Guide to Comparing Orlando Insurance Quotes
Compare Orlando Insurance Quotes With Confidence
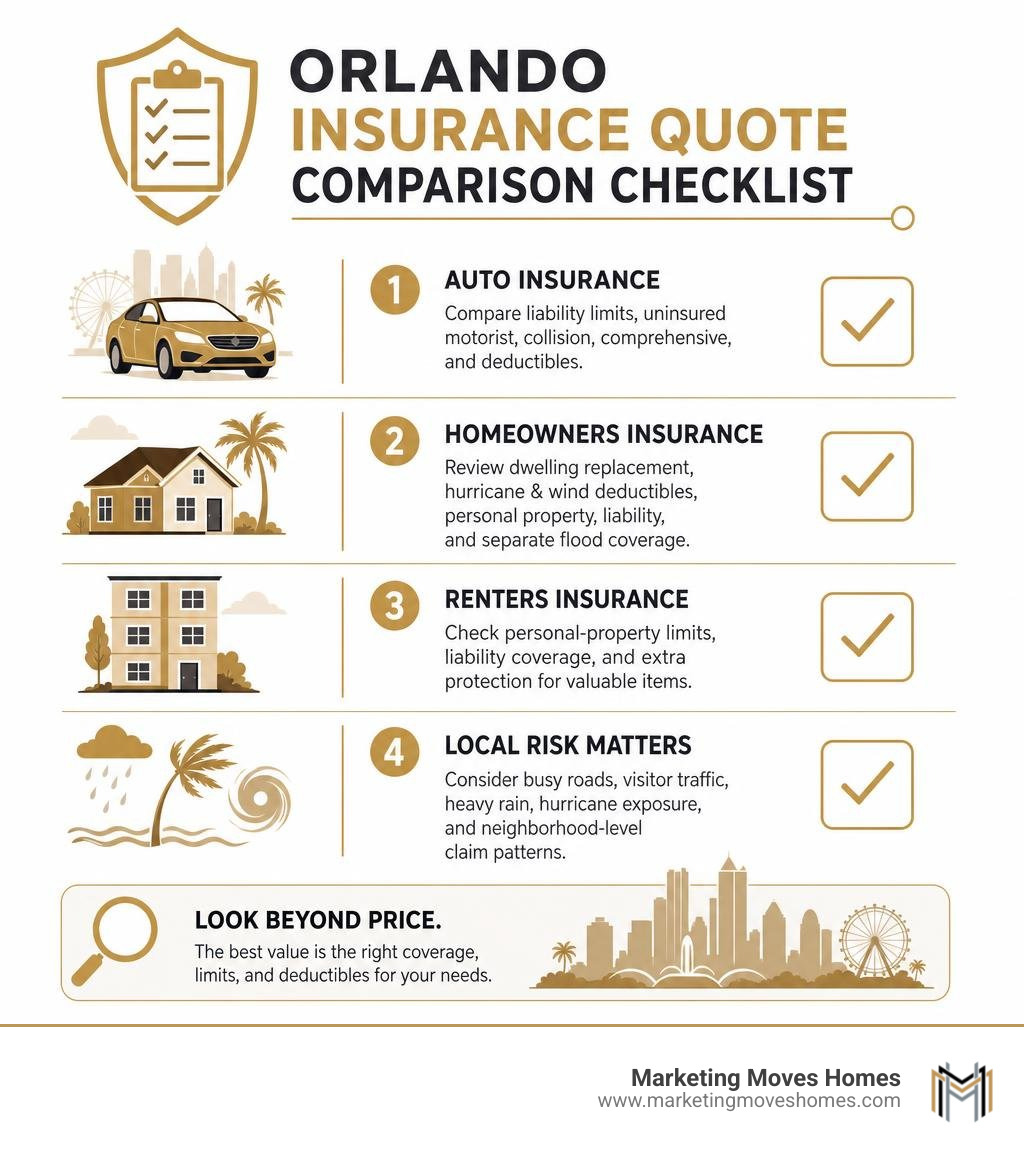
Orlando insurance quotes can vary widely based on the coverage you choose, where you live, your driving or claims history, and the risks tied to Central Florida weather and traffic. For a quick, useful comparison, request matching quotes from several insurers and review more than the premium alone.
- Auto insurance: Confirm Florida-required coverage, then compare liability limits, uninsured motorist protection, collision, comprehensive, and deductibles.
- Homeowners insurance: Compare dwelling replacement coverage, hurricane and wind deductibles, personal property protection, liability, and separate flood coverage.
- Renters insurance: Check personal-property limits, liability coverage, and whether valuable items need extra protection.
- Local risk matters: Orlando’s busy roads, visitor traffic, heavy rain, hurricane exposure, and neighborhood-level claim patterns can all affect a quote.
For homeowners and buyers in Lake Nona, including the 32827 and 32832 ZIP codes, insurance is an important part of evaluating the true cost and protection needs of a Central Florida home. A low premium can be appealing, but it is only a good value when the policy’s limits, exclusions, and deductibles fit the property and your financial comfort level.
I am Scott Brazdo MBA, Co-Founder of Marketing Moves Homes and a Central Florida REALTOR with deep experience helping clients assess the practical details around buying, selling, and protecting homes in Orlando and Lake Nona. Through that work, I have seen why clear comparisons of Orlando insurance quotes matter before a move, purchase, or policy renewal.
Simple Orlando insurance quotes word guide:
Central Florida Auto Insurance Requirements and Rate Drivers
Navigating Central Florida’s roadways requires an understanding of how local environment and traffic dynamics affect auto protection. In Orlando, auto insurance rates are driven by a combination of dense commuter corridors, substantial tourism volume, and regional weather hazards. Major arteries like Interstate 4 witness heavy daily congestion where local commuters mix with tens of millions of visiting tourists who may be unfamiliar with regional exits, navigation patterns, and sudden afternoon downpours.
When reviewing Orlando insurance quotes, it helps to understand how drivers select coverage beyond basic legal minimums. The baseline requirements in Florida mandate Property Damage Liability (PDL) to cover damage caused to other vehicles or structures, alongside Personal Injury Protection (PIP) designed to address immediate medical bills and lost wages regardless of fault. Following statutory updates, Florida auto insurance regulations have evolved, placing renewed emphasis on Bodily Injury Liability (BI) to handle medical claims for other parties injured in an at-fault collision.
Because Florida experiences a high proportion of uninsured or underinsured drivers, with many motorists operating on local roads without adequate policies, carrying Uninsured Motorist (UM) protection is a vital consideration. Furthermore, Collision coverage steps in to repair your vehicle following a crash, while Comprehensive coverage protects against non-collision hazards common in Central Florida, such as falling oak branches during tropical storms, windshield chips, theft, or localized street flooding.
Impact of Driving Record, Credit Score, and ZIP Codes
Insurance carriers evaluate risk using specialized underwriting criteria that examine a driver’s age, driving record, credit-based insurance score, and geographical location down to the specific ZIP code. Younger drivers or those with recent traffic violations or at-fault accidents generally face higher rates due to statistical risk profiles. Additionally, insurers utilize credit-based scores as a key metric to predict claim likelihood.
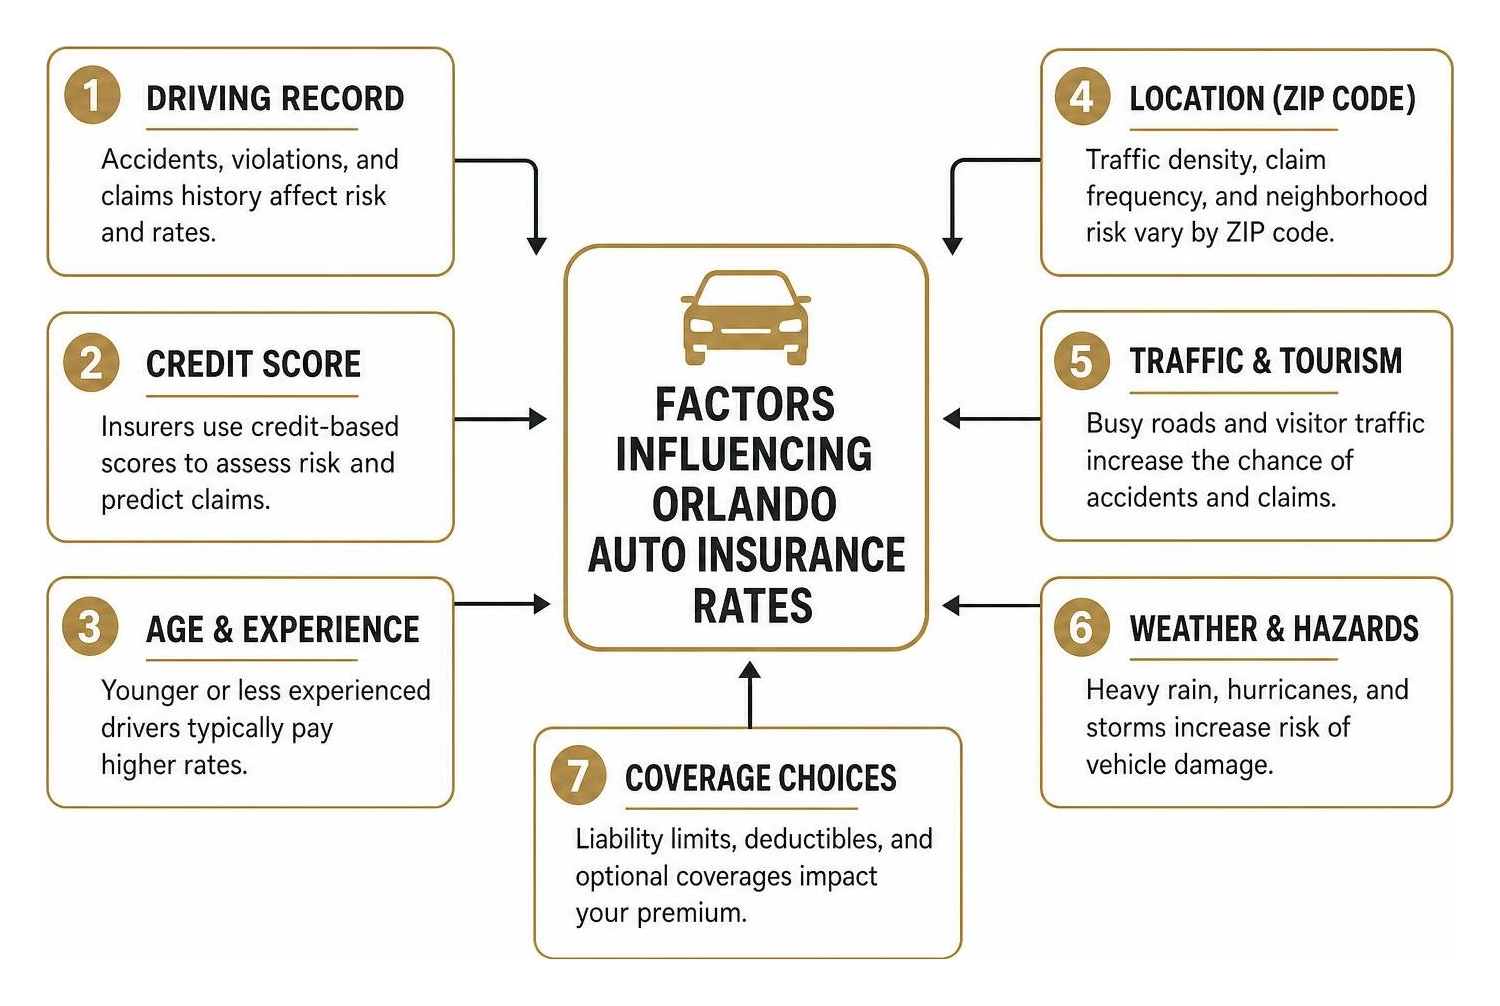
Location within Orange County heavily influences premium pricing. Neighborhoods with higher traffic density or frequent claim reports experience distinct rate structures compared to quieter suburban developments. For instance, residents in Lake Nona’s premier master-planned developments within the 32827 and 32832 ZIP codes benefit from modern infrastructure, planned access roads, and lower historical incident density than older, heavily congested urban corridors. To see how geographical factors influence vehicle policy costs across Central Florida, drivers often review an Orlando auto insurance cost analysis.
Legal Minimums, Uninsured Driving Penalties, and SR-22 or FR-44 Filings
Operating a motor vehicle in Florida without continuous auto coverage triggers severe legal and financial consequences. Florida operates with zero grace period for lapses in coverage. If a policy terminates without immediate replacement, the Department of Highway Safety and Motor Vehicles (FLHSMV) can suspend your driver’s license and vehicle registration, requiring administrative reinstatement fees and proof of financial responsibility.
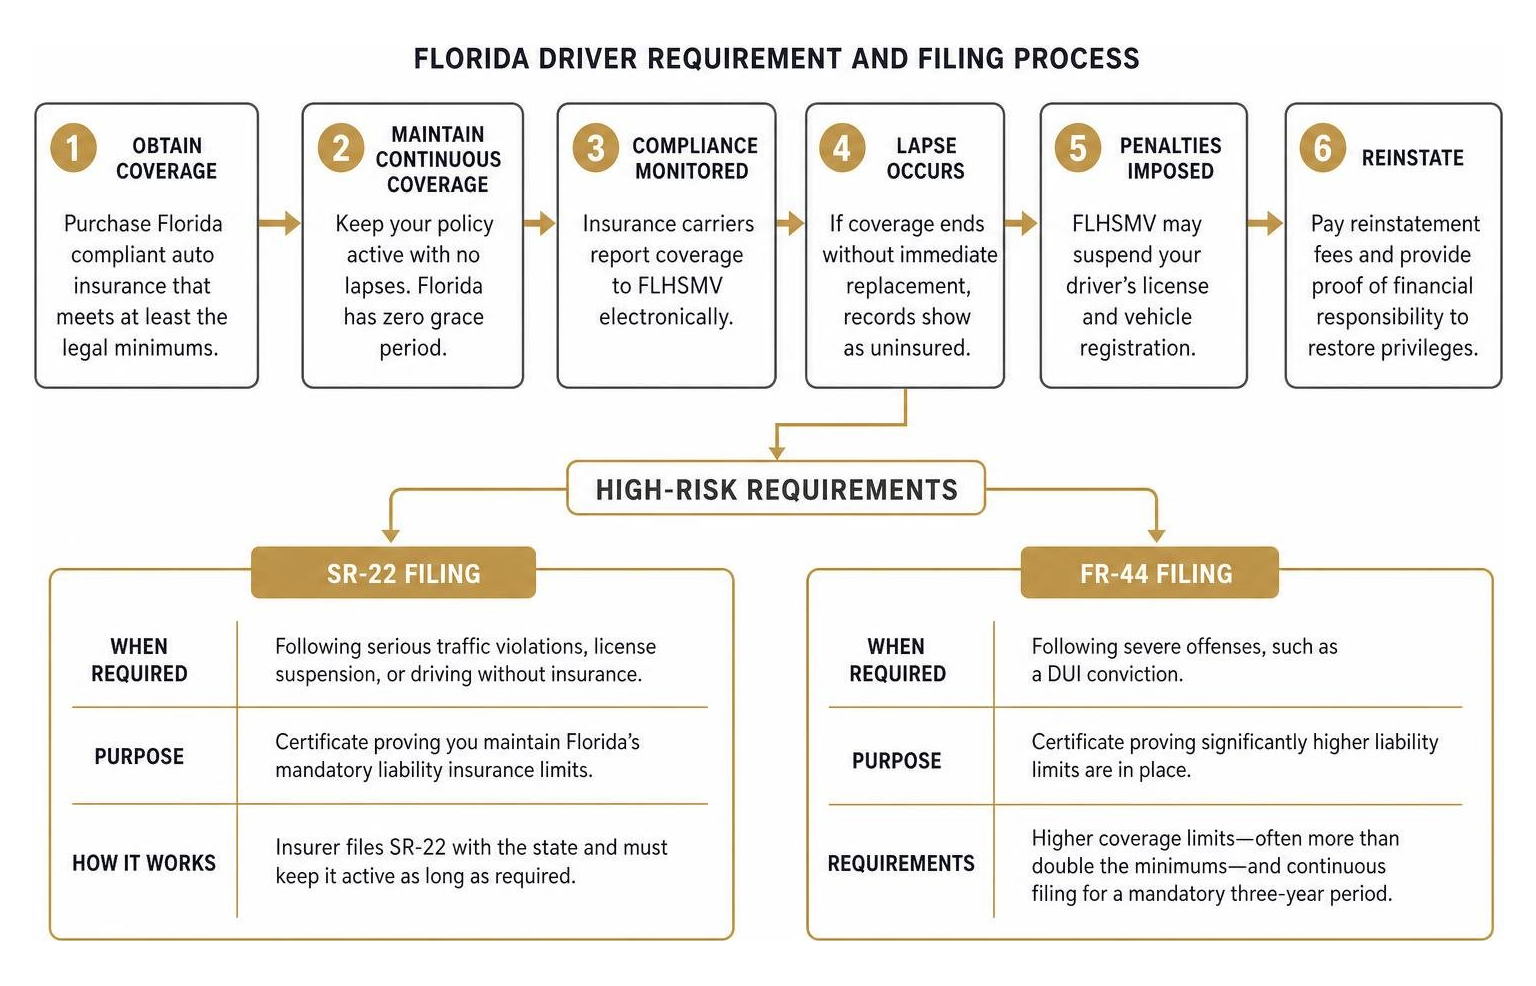
For high-risk driving circumstances, state authorities require specific regulatory certificates:
- SR-22 Filing: A court- or state-mandated certificate demonstrating that a driver maintains Florida’s mandatory liability insurance limits following severe traffic infractions, license suspensions, or driving without active insurance.
- FR-44 Filing: A certificate required following severe offenses, such as a Driving Under the Influence (DUI) conviction. An FR-44 requires significantly elevated liability protection limits—often more than double standard legal minimums—and must remain continuously active for a mandatory three-year period without lapse.
Homeowners and Renters Coverage Options in Orlando
Securing comprehensive property insurance in Central Florida requires evaluating specific structural and environmental risks. A standard homeowners policy (HO-3) protects your primary building structure under Dwelling Coverage, while Other Structures handles unattached garages, fences, or storage sheds. Personal Property Coverage protects furniture, electronics, and clothing, while Loss of Use provides living expenses if a severe storm renders your dwelling temporarily uninhabitable.
Renters insurance (HO-4) offers an affordable way for tenants in Lake Nona apartments and rental homes to protect personal property and secure personal liability coverage, as a landlord’s master policy only protects the physical building structure itself. Whether owning a multi-story home in Lake Nona’s 32832 community or renting near Medical City, selecting full replacement cost coverage rather than actual cash value ensures items are replaced at current retail values rather than depreciated amounts.
Evaluating Homeowners and Renters Orlando Insurance Quotes
When examining property insurance proposals, dwelling limits should reflect total reconstruction costs rather than the property’s market value or real estate purchase price. Building costs depend on current local labor rates, material availability, and current Florida building codes.
Older roofs represent one of the most critical elements in Florida property underwriting. Homes with roofs approaching 15 to 20 years of age often face strict underwriting inspection guidelines or higher wind deductibles unless upgraded. Balancing your annual premium against comfortable out-of-pocket deductible levels ensures you retain financial resilience during a claim.
| Policy Coverage Component | Standard HO-3 Protection | Recommended Optional Endorsement |
|---|---|---|
| Dwelling (Coverage A) | Rebuilds main structure based on estimated construction costs | Extended Replacement Cost (adds 10–25% buffer for material spikes) |
| Personal Property (Coverage C) | Covers personal items against named hazards | Scheduled Personal Property (for jewelry, art, or high-value electronics) |
| Windstorm / Hurricane | Included subject to a separate percentage deductible | Roof Surface Payment Schedule endorsement or Wind Mitigation upgrades |
| Water Damage / Flood | Covers sudden internal plumbing bursts | Separate Flood Policy (covers rising surface water and lake overflows) |
| Personal Liability | Protects against bodily injury or property damage claims on-site | Personal Umbrella Policy (extends protection limit across home and auto) |
Weather Hazards, Hurricane Deductibles, and Flood Risks
Central Florida’s weather patterns dictate specialized insurance considerations. While inland locations like Orlando enjoy protection from direct coastal storm surges, severe tropical systems still bring tropical-storm-force winds, high gusts, torrential rainfall, and localized lightning damage. Standard homeowners policies feature a separate Hurricane Deductible, structured as a percentage (typically 2% to 5%) of the total insured dwelling value rather than a flat dollar fee.
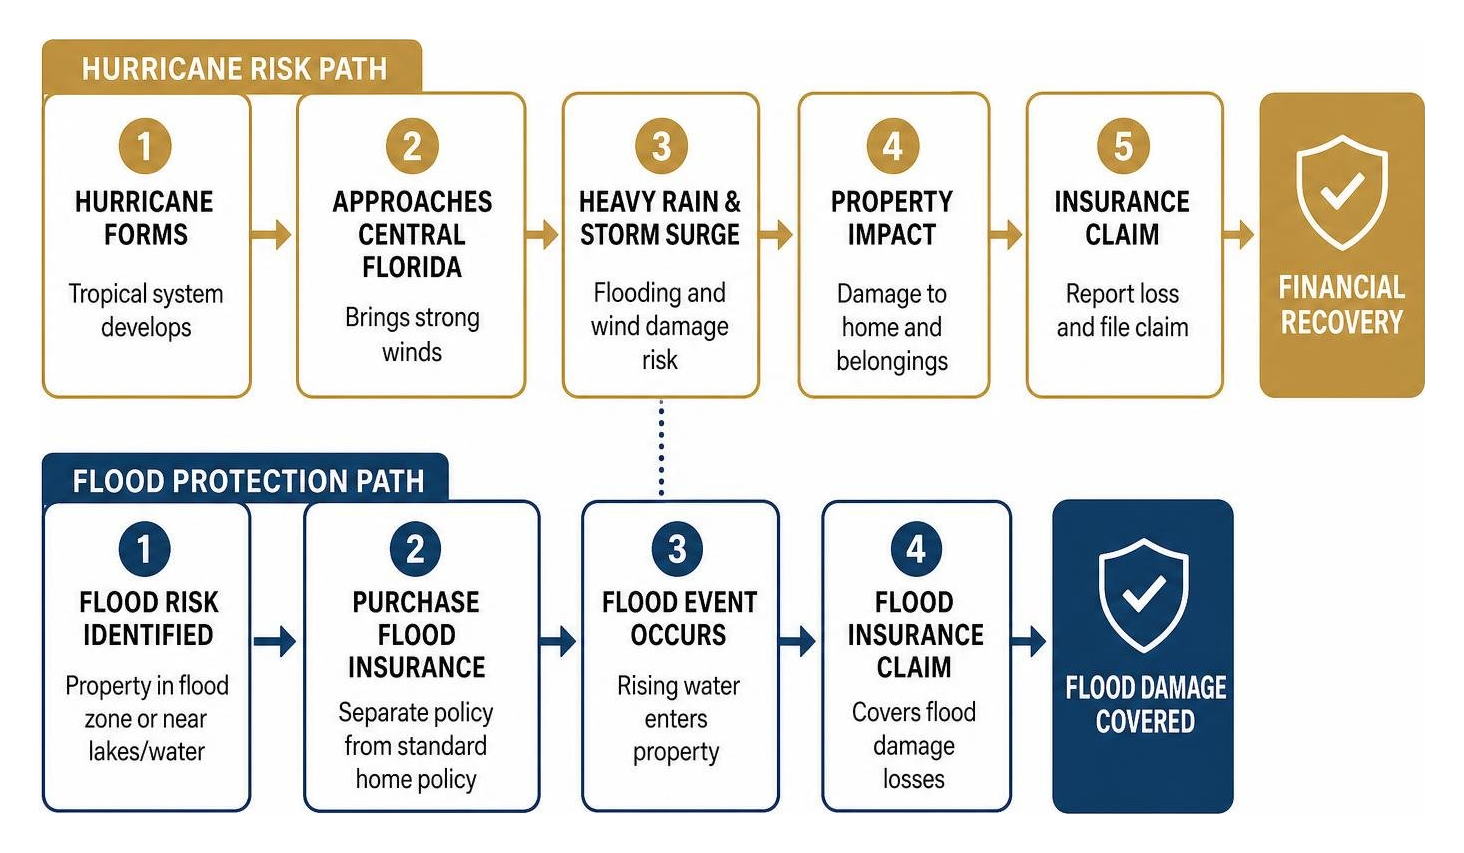
Standard home policies strictly exclude flood damage resulting from rising water or surface runoff. Because many properties across Central Florida lie within identified flood hazard areas or near lakes and retention systems, purchasing standalone flood insurance is essential. To lower windstorm premiums significantly, homeowners can arrange a Wind Mitigation Inspection. A certified inspector checks roof attachment clips, hip roof designs, hurricane straps, and window protection to unlock substantial policy credits. Local communities in 32827 and 32832 frequently incorporate these wind-resistant building techniques. Residents exploring regional insurance nuances can consult Lake Nona local insurance insights.
Smart Strategies to Lower Your Orlando Insurance Quotes
Reducing total policy overhead in Central Florida does not require sacrificing necessary coverage. Drivers and homeowners can implement several strategic adjustments to streamline their annual premiums:
- Policy Bundling: Combining auto and homeowners policies with a single insurer yields substantial multi-policy discounts.
- Telematics Driving Apps: Enrolling in safe-driving mobile applications allows carriers to reward gentle braking, moderate speeds, and low night driving with safe driver discounts.
- Adjusting Deductibles: Choosing slightly higher deductibles for collision or standard home property claims reduces monthly premiums while maintaining catastrophic protection.
Maximizing Policy Savings and Premium Discounts
Unlocking stackable savings options allows policyholders to keep coverage robust while lowering annual expenditures. Insurers offer multi-car discounts for insuring several household vehicles together, good student discounts for high-achieving young drivers, and paid-in-full discounts for settling annual policy balances upfront. For home policies, completing wind mitigation inspections and installing monitored burglar alarms, smoke detectors, or smart water leak shut-off devices provides continuous policy credits.
Avoiding Common Pitfalls When Securing Orlando Insurance Quotes
When comparing insurance proposals, policyholders occasionally make costly structural errors:
- Underinsuring the Structure: Selecting dwelling protection based on loan balances rather than true local rebuild construction expenses.
- Allowing Coverage Lapses: Changing carriers without aligning effective dates, resulting in legal driver penalties or home policy non-renewals.
- Ignoring Flood Exposure: Assuming inland location protects against rising surface water, heavy downpours, or retention basin overflows.
- Selecting Inadequate Liability Limits: Retaining minimum liability limits that leave personal assets exposed during a major auto collision or property claim.
Frequently Asked Questions About Central Florida Coverage
What is the average cost of car and homeowners insurance in Orlando?
Insurance pricing varies significantly depending on personalized underwriting factors including driving history, credit score, vehicle year, neighborhood ZIP code, home age, and structural roof rating. Auto coverage pricing reflects traffic volume and commuter routes, while home insurance rates depend heavily on construction materials, wind mitigation features, and flood zone proximity. Rather than relying on generic estimates, requesting customized quotes from multiple carriers provides the most accurate assessment.
What auto insurance coverage is mandatory for drivers in Florida?
Florida law requires all registered motor vehicles to carry Personal Injury Protection (PIP) to cover medical expenses and lost wages, alongside Property Damage Liability (PDL) to pay for structural or vehicular damage caused to others. Following legislative updates, drivers must also satisfy Bodily Injury Liability (BI) requirements to protect against injury claims arising from at-fault accidents. Maintaining continuous coverage without lapse is strictly enforced across the state.
How do hurricane deductibles and wind mitigation affect home insurance premiums?
Hurricane deductibles represent a percentage of your home’s total insured dwelling value rather than a fixed dollar amount. Choosing a higher percentage deductible lowers annual premium costs but increases out-of-pocket expenses when filing a storm claim. Completing a Wind Mitigation Inspection allows homeowners to demonstrate structural features—such as hurricane straps, hip roof geometries, and secondary water barriers—which generate significant ongoing premium discounts.
Conclusion
Evaluating Orlando insurance quotes thoughtfully ensures your vehicles, household belongings, and property investments remain thoroughly protected against regional weather events and busy roadways. In Lake Nona and across Central Florida, aligning adequate policy limits with strategic discounts yields long-term financial stability.
When buying or selling a home in Lake Nona’s 32827 and 32832 ZIP codes, understanding total housing overhead—including property protection—is a key part of smart real estate planning. As local listing experts and neighborhood authorities, our team at Marketing Moves Homes provides expert guidance to help buyers and sellers navigate every stage of their transaction smoothly.
Automated third-party online valuation tools frequently deliver inaccurate home estimates because they lack insight into recent property upgrades, custom interior features, micro-neighborhood nuances, and current Lake Nona market dynamics. For a clear, professional valuation of your property, reach out to us directly.
Whether you are preparing to list your property for top dollar using our high-impact listing strategy or seeking your dream residence in Central Florida, we are here to deliver exceptional results. Ready to begin your real estate journey? Contact our team to explore options to buy a home in Orlando or explore Orlando property resources today.